
August 8, 2025
More and more economists are suggesting that the economy is about to enter a period of “stagflation” which is characterized by a combination of high inflation, stagnant economic growth, and high unemployment. We disagree with all three parts of that description. Having said that, the reality is that all economists are trying to assess the outcome of policy changes introduced by the Trump Administration. The imposition of tariffs, layoffs of federal government workers, and the deportation of thousands of migrant workers has complicated the issue. Economists love to rely on history as a guide but, in this case, there are no comparable periods to help us. As a result, we are all largely guessing. In addition to uncertainty regarding the economic situation, Trump is attempting to politicize the Fed by stacking the deck with people who share his view that interest rates are far too high. In our opinion, the Fed currently is correct in keeping the federal funds rate steady. What happens next depends upon whether a stagflation scenario actually unfolds.
With respect to inflation the consensus is that tariffs are going to boost the prices of many imported products. That is true to some extent. But consumers presumably will then shift their purchases to a lower-priced domestically produced good. In a weighted measure of inflation, such as the personal consumption expenditures deflator, greater weight will be given to the lower-priced good which should keep that particular measure of inflation in check.
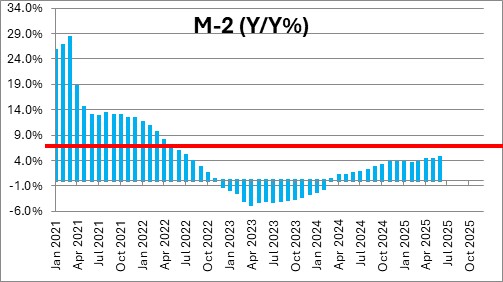
In our opinion, a prolonged increase in inflation will occur only if the Fed lets the money supply grow too quickly – such as occurred in the 2020-2021 period. At that time the Fed purchased several trillion dollars’ worth of U.S. Treasury securities which created considerable surplus liquidity in the economy, money growth exploded, and inflation soared. The Fed then shrank its portfolio for a protracted period of time, money growth declined, the surplus liquidity largely disappeared, and inflation slowed considerably. After declining for a couple of years, slow money growth has returned. In the past year its growth rate has been 4.5%. In the past six months money growth has been 5.4%, and in the past three months it has been 6.7%. The Fed seems intent on getting money growth back to its long-term average pace of around 6.0%. As long as the Fed continues on that course we do not envision any long-term pickup in inflation.
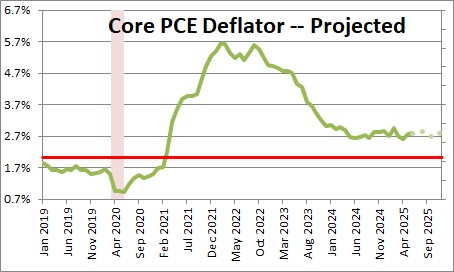
The Fed expects the core personal consumption expenditures deflator to increase 3.1% this year and then slow to 2.4% in 2026. We peg it at 2.8% this year and 2.4% next year. The Fed targets growth in this inflation measure at 2.0%. While it is likely to grow at a pace slightly faster than desired, it is unlikely to accelerate. That doesn’t sound like a problem with the -flation part of the stagflation concept.
GDP growth contracted by 0.5% in the first quarter as Trump’s initially-announced tariffs scared consumers and business leaders alike. With the first quarter decline in GDP the year-over-year growth rate slowed considerably relative to the 2.5% growth rate registered in 2024, Economists generally view that as evidence that the economy has slowed considerably. But second quarter growth rebounded to 3.0%. And, while it is still early, third quarter growth seems likely to climb by 2.5%. It appears to us that tariff policies had a major negative impact on growth early in the year, but since then trade agreements and the lowering of most tariff rates from what they were initially, have mitigated much of that fear.

The Fed believes that the long-run potential GDP growth rate is 1.8%. With the GDP decline early in the year It expects GDP growth of 1.4% in 2025 . We peg it at 1.8%. That does not seem to fit with the stag- part of the stagflation scenario.
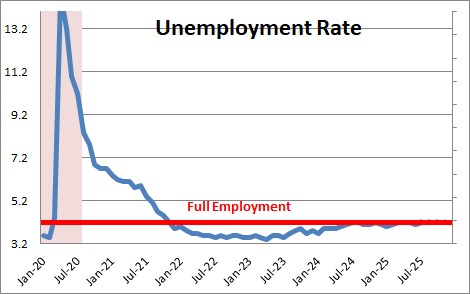
Finally, the unemployment rate currently is 4.2%. While employment growth has slowed, so too has growth in the labor force. As a result the unemployment rate has been quite steady. The Fed believes the full-employment level of the unemployment rate (the rate at which everybody who wants a job has one) is 4.2%. It expects the unemployment rate to be 4.5% at the end of 2025 and 2026. We expect it to be 4.2% at the end of both years. Any way one slices it, the economy does not appear to be headed for any significant problem in the labor market which is the third leg of a stagflation scenario.
With the inflation rate, GDP growth, and the unemployment level currently not far from what the Fed would like to see, it seems justified in maintaining the funds rate in a range from 4.25-4.5%. Having said that, the Fed seems eager to ease and anticipates a 0.5% reduction in the funds rate by yearend. It already has two FOMC members wanting to cut rates immediately and with the addition of Trump ally, Stephen Miran, at the September 16-17 FOMC meeting there may be three Fed officials leaning in that direction. But that meeting is still five weeks away. To justify a September easing move the Fed needs to see evidence that the economy has slowed further, the unemployment rate is definitively on the rise, and/or the inflation rate is subsiding. We do not think that any of those things are likely to happen, but time will tell.
Stephen Slifer
NumberNomics
Charleston, S.C.


Stephen, thank you for a level-headed, well thought analysis of the confusing economic situation we find ourselves in. I really appreciate your wisdom and your ability to see through the fog.
Full Speed Ahead.
Hi Darrel. Like my response to Taylor below I somehow missed your comment as well. So sorry about the delayed response. Everybody has bought into the scenario where tariffs are going to slow growth, boost inflation, and the Fed is going to ease twice between now and yearend. As I mention in my commentary this week, I think that a lot of those views about the economy are drawn from the internet. Who really has the time to sit down and churn through the massive amount of data that are available? So people get their opinions about the economy from what they read. And our mainstream media and social media highlight the weak growth, escalating scenario. It is news and it is exciting. Who wants to hear that the economy continues to plod along and nothing too exciting is happening.
The Fed should not but may ease in September. But if they do so it will reinforce my belief that this group at the Fed has become very political. We saw it in 2021 and 2022 when the Fed refused to tighten despite the fact that inflation was climbing out of control. It believed the acceleration was temporary. Did the Board staff simply have a lousy forecast? Or did politics play a role? Last year the Fed suddenly decided to ease by 50 bps two weeks before the election when everybody expected a cut of 25 bps because they thought the labor market was weakening rapidly. Once again, did the Board staff have a lousy forecast? Or was it politically motived? Now, as I see it, we are a month away from the next FOMC meeting. The economy seems to be hanging in there. The early consensus appears to be for about 2.5% GDP growth in the third quarter. The labor market does not seem to be weakening. And inflation is steady. It is not slowing and heading towards the 2.0% target. And the PPI data for July make me wonder if businesses will pass along those higher costs to consumers in the months ahead. Does not strike me as a situation in which the Fed should be easing. If they cut rates in September it will provide further evidence to me that the group at the Fed now is far more concerned with politics than other groups I have both worked with and observed for the past 50 years.
Best. Steve