October 27, 2026
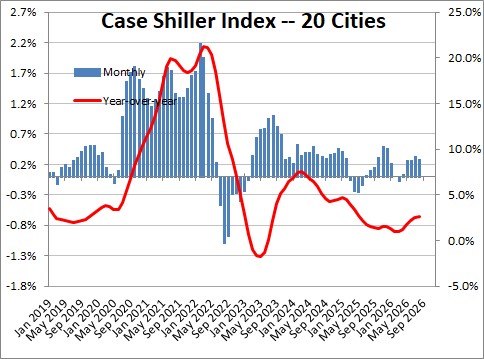
The seasonally adjusted Case Shiller Index of Home Prices in 20 cities rose 0.3% in August after having risen 0.3% in July. Prices have risen 2.6% in the past year.
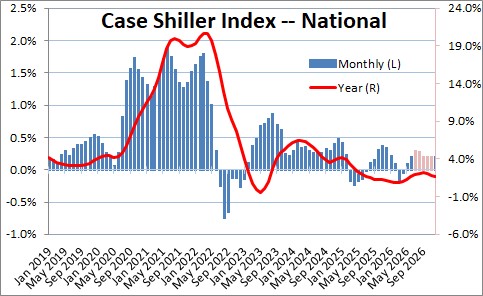
The National Index which is a slightly broader measure of home price rose 0.3% in both July and August, The year-over-year increase for this series is 2.1%. Home prices have basically flattened out.
Rebecca Kaufman, Associate Director of Commodities at S&P Dow Jones Indices said, “U.S. home prices declined in real terms for the 15th consecutive month in August 2026.” She added that, “Affordability, however, remains challenging. With inflation at 3.4%, Brent crude near $100 per barrel and mortgage rates in the mid-to-high 6% range, households continue to face elevated costs alongside persistently high home prices.”
To figure out what is likely to happen to home prices in 2027 we like to focus on housing affordability. There are three pieces to this equation. First, home prices should edge lower in the months ahead.
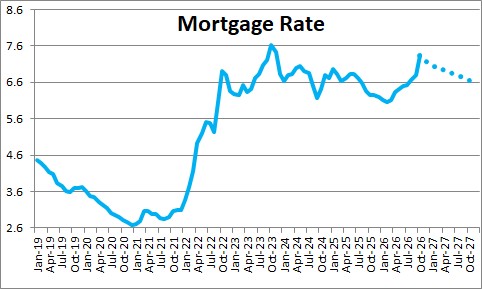
Second, mortgage rates are currently at 7.3% and should decline slightly to 6.6% by the end of next year.
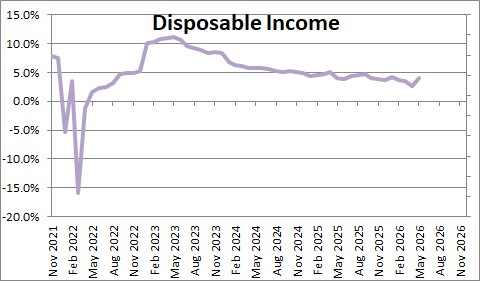
Third, job gains and wage hikes are boosting consumer income. Disposable income has increased by 4.8% in the past year and should continue to climb slowly.
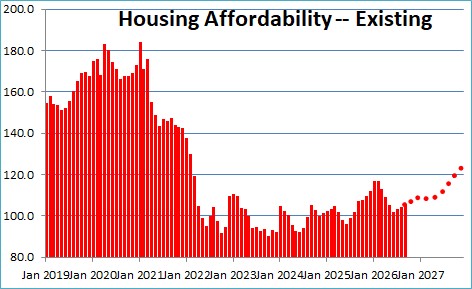
The housing affordability index had been tracking at about 105 for many months which means that potential buyers had 5% more income than required to purchase a median-priced home. With income continuing to rise slowly, with mortgage rates declining slightly, and home prices likely to edge lower, a median income earning family should have about 25% more income than required to purchase that median-priced home by the end of 2027 That should put some spark back into both new and existing home sales.
We expect GDP to climb by 3.5% in the third quarter and 2.6% in 2026. We then look for growth of 2.8% in 2027. The ratio of consumer debt to income remains very low. The economy keeps cranking out jobs and wages keep rising slowly which should boost consumer income and spending. AI is causing investment spending to soar. Mortgage rates are likely to fall slightly in the months ahead as inflation edges lower. The economic environment seems favorable.
The shelter component of the CPI seems to closely track the Case Shiller change in home prices with a lag of about a year. As a result, the shelter component of the CPI which has increased 3.2% in the past year should slow further and increase 1.8% in 2027. That should allow the core CPI to resume its slowdown.

Stephen Slifer
NumberNomics
Charleston, SC


Steve – To what extent do the accelerating housing prices affect overall inflation?
Hi Frank,
Home prices are an asset and are treated as a capital investment. So we cannot look at housing prices and easily figure out what is happening to inflation. The CPI is a measure of inflation and what goes into the CPI is a measure of rent. In fact, rents are about 1/3 of the entire CPI. If rents are on the rise, that feeds directly into that measure of inflation.
The Census Bureau does a quarterly survey on homeownership. Amongst the many things they report are “Asking Rent — Vacant Rentals”. I cannot show you the chart using WordPress so I will send it your e-mail address. In the four-quarter period ending in the third quarter rents had risen 15.8%. But yet in the CPI rents have risen just 1.9%. But remember that in the CPI they knock on doors and ask people how much their rent is, and they survey the same unit every six months. So given that method of calculation rapid rent increases may take a while to get captured.
Bottom line is, rents are going up. But expect them to rise more slowly than the rapid increases in home prices. If they have risen 1.9% in the most recent 12-month period they should be higher — 2.5% perhaps — in 2021.
Hope this helps.
Steve