
September 23, 2026
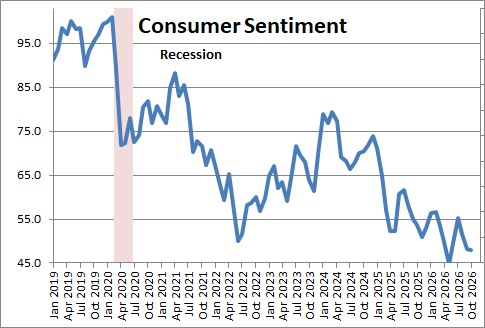
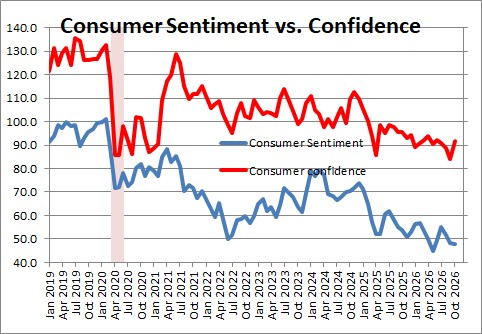
The final estimate of consumer sentiment for October fell 0.1 to 48.0 after having declined 3.6 points .in September.
Surveys of Consumers Director Joanne Hsu said, “Consumer sentiment held steady this month, registering a scant one-tenth of an index point below September. Increases in sentiment among Republicans and Democrats were balanced by declines among independents. While year-ahead business conditions improved about 14%, they stand 16% less than last October’s read. This month’s decline in the Current Conditions subindex was driven entirely by buying conditions for durables, which plunged 18% on the basis of higher interest rates and rising concerns about the affordability of such purchases. Purchasing power continues to dominate consumer views of the economy. Sentiment is now 10% below a year ago and 15% less than February, just prior to the Iran conflict.”
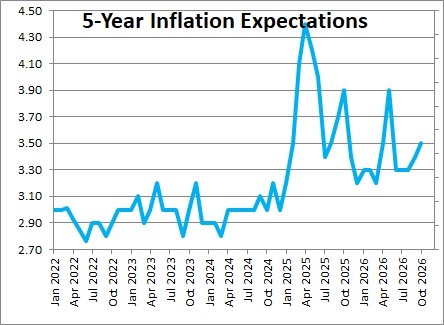
She added that, “Year-ahead inflation expectations ticked up from 4.6% last month to 4.7% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations also stepped up from 3.4% in September to 3.5%, notably higher than their 2024 range of 2.8% to 3.2%”
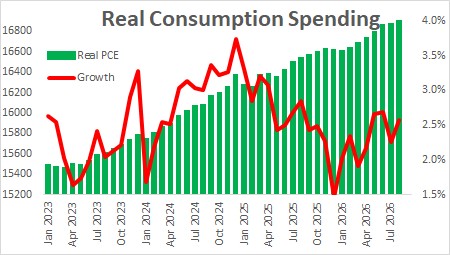
There has been a rather dramatic drop in confidence since the beginning of this year. The last time that confidence was this low was in 2022 when inflation was at its peak. But the steep drop then never translated into a reduction in consumer spending. In recent months the pace of consumer spending has been holding up relatively well as consumers rely on some of their stock market gains to support spending. The relationship between confidence and spending has not worked well for the past several years.
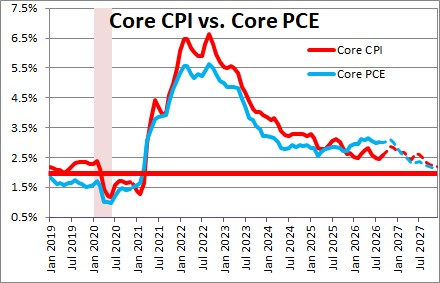
The uncertainty regarding policy, tariffs in particular, is taking a toll. In fact, as noted above, 5-year inflation expectations rose to 3.5% as consumers continue to fret about the potential impact of tariffs and now the prospects for oil prices. In our opinion, a big pickup in the inflation rate seems highly unlikely. Consumers appear to be overly concerned. Over a 5-year period we expect inflation to be roughly in line with the Fed’s 2.0% target. Over a 10-year period the Treasury market’s inflation-indexed 10-year note yield implies a 2.3% increase in inflation.
Both the University of Michigan’s consumer sentiment index and the Conference Board’s measure of consumer confidence have fallen sharply. The two series can diverge from one month to the next, but the trends are similar.
We expect 3.5% GDP growth in Q3 and 2.6% growth in 2026. We also expect GDP to increases 2.8% in 2027.
Consumers’ assessment of current conditions fell 4.2 points from 50.9 to 46.7
Consumer expectations for six months from now rose 2.5 points from 46.3 to 48.8.
Stephen Slifer
NumberNomics
Charleston, SC


Going forward to the next reporting point will consumers focus on President Trump’s positive commentary for “Negative Interest Rates” and “Refinancing the US debt”
Since a lot of folks have savings accounts one would think :negative interest rates” would create negative consumer sentiment
Most people associate “refinancing” with financial difficulties
I wonder if that will have a negative on consumer sentiment
HI Allen,
Good question. But, at least in my mind, it is a moot point here in the U.S. I don’t think we will ever see negative rates but, then again, some of these other countries around the globe never thought they would get there either. If we should get to the point where negative rates become possible let’s keep an eye on confidence as you suggest. The soonest that might occur would be in the midst of the next downturn — whenever that is.
Steve
Steve
The rise in inflation and interest rates appears inevitable.
I am concerned about the effect this will have on our ability to meet our federal debt obligations.
At some point in the future will we reach a tipping point where cannot pay the interest on the debt?
Then what happens?
Hi Bill,
I have been worried about debt for some time. The path we are on seems unsustainable to me. Debt as a percent of GDP has climbed to 103%. The record was 106% right after WWII. But at that point you cut defense spending sharply and the ratio shrank quickly. This time 70% of the deficit each year is entitlements. Those will be difficult to cut and, hence, the ability to shrink the deficit to something manageable (3% of GDP) is unlikely.
Specifically, with re: to your question about inflation, inflation helps to shrink the deficit. If we get nominal GDP growth of, say, 10% (4% real growth + 6% inflation) revenue growth should be roughly 10%, Yes, interest rates will rise, and interest on the debt outstanding will climb. At the same time some government expenditures will shrink (think welfare payments, Medicaid). An easy way to resolve the budget/debt problem is some good old fashioned inflation.
While inflation may help the government, it hurts the rest of us, especially older people trying to live on a fixed income, and lower income individuals who do not get the benefits of higher home prices and higher stock market valuations.
The reality is that debt/GDP of 103% is not sustainable. If we have a problem like in 2020, when the Treasury loses tax receipts and government spending increases, the budget deficit explodes, and debt in relation to GDP takes a huge jump. Having said that, I have been worried about debt for ages and nothing bad has happened — yet. That does not suggest that we are supposed to ignore it. There will be a day of reckoning, but you and I may not be around to see it.
Steve- great information, is there any data on the distribution of consumer net worth i.e. is it even across income levels or aggregated in one or more segments? Could this explain some of the differences in consumer sentiment?
Hi George. Net worth is decidedly NOT evenly distributed. I have not looked for that information specifically, but just a quick check I found online which seems to give us a sense. It turns out that a PEW Research Center study noted that upper income families (which I guess it defines as income greater than $207,400 in 2018) held 79% of the wealth. The middle income group which I guess ranges from $28,700 in 2018 to $207,400 held 17% of the wealth, and the lower income category (less than $28.700) had 4%. The data are obviously old, but I am sure the numbers have changed not all that changed much. The bulk of that wealth comes from the stock market and home ownership. Thus, low income earners do not share much in the wealth of the country. Middle income earners have more, but still relatively little. The wealthier Americans have by far the biggest share of the pie. Thus, it seems to make sense that if you do a survey of consumer confidence, lower income earning families included in the survey are being hit hard and their confidence has plummeted. A big portion of their income goes to housing, gas, and food — all of which have risen sharply in price. They were just getting by before and now they have to make a choice — Pay the rent? Buy food for the family? Fill the car with gas?
But what bothers me the most is that the U of Michigan survey has confidence plummeting — below the 2020 low, and below the 2008-09 recession low. I am not sure that makes sense to me. The Conference Board measure of consumer confidence has it dropping, but the decline is not nearly as dramatic. So which is the better measure? The Conference Board data seem more consistent with the consumer spending data — some slowdown but not dropping off a cliff. I guess we will see.
Steve
another great article, Steve! Thanks as always
Thanks Michelle. Nice to hear from you. Hope all is well.