November 12, 2026
.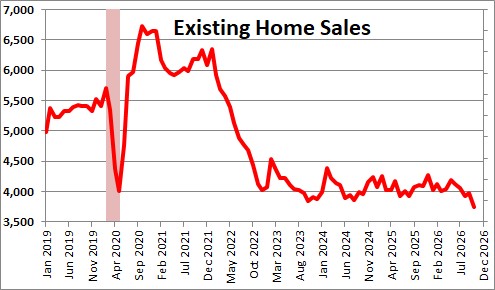
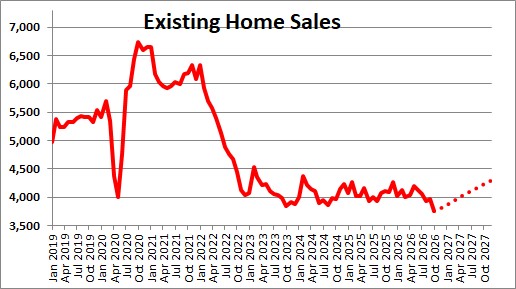
Existing home sales fell 5.5% in October to 3,750 thousand after have gained 1.0% in September. That is the slowest pace of existing home sales since 2010. The recent increase in mortgage rates to 7.3% apparently reduced sales significantly.
Lawrence Yun, NAR chief economist said that, “Home buying is difficult when mortgage rates have climbed to their highest levels since 2000, aside from a single month in 2023. As a result, home sales fell to their lowest level since August 2010,” He added that, “Despite fewer transactions in October, the 88 million homeowners across the country are largely in a comfortable financial position due to sizable housing wealth accumulation. Based on the current underwhelming home sales pace at a time of consistent job growth, there could be sizable pent-up demand if mortgage rates decline.”
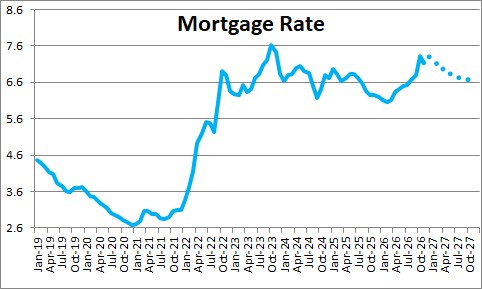
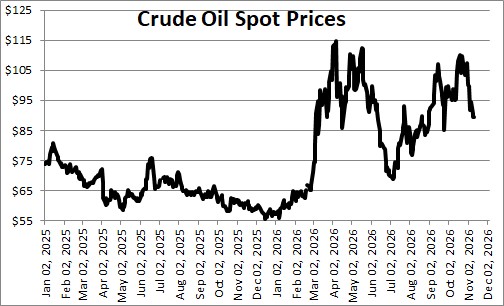
Mortgage rates have risen to 7.3%. The war in Iran has curtailed the flow of oil from the Mideast and oil prices climbed from $65 before the war to about $110 as recently as October 19. But oil prices have fallen sharply, especially since the election, are are now at $89 as traders seem to be making the bet that Trump will not re-escalate the war. If that is the case oil prices can fall farther. Oil has been a major source of the upswing in inflation this year. If oil prices remain at their current level or fall farther it will help to bring down the inflation rate in 2027. For what it’s a result, the CPI should come in at this year to 3.6% but then slow to 2.3% next year. The core rate should be 2.9% this year, but the combination of subdued growth in the money supply, a slight decline in home prices and rents, and a small gain in unit labor costs should lead to an inflation rate of 2.3% in 2027. If that is the case we expect mortgage rates to inch lower from 7.3% currently to perhaps 6.6% by the end of next year as inflation subsides.
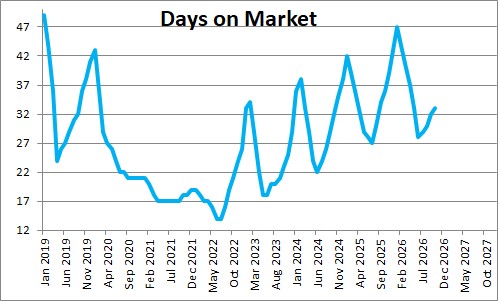
The average home sat on the market for 33 days in October which is up from 32 days in September and 36 days in October of last year .. That is still a relatively short time period by any historical standard, but it is not as short as it used to be. The housing market has clearly softened, but it has not collapsed.
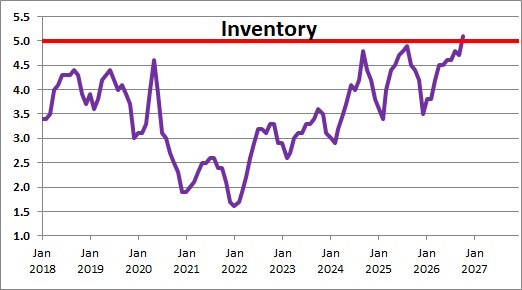
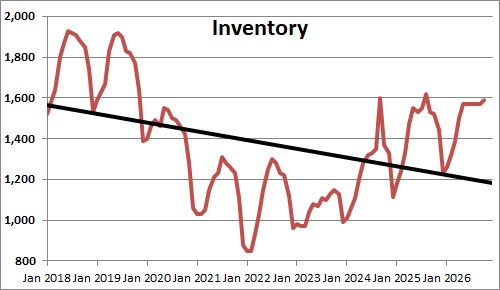
There are still relatively few homes available for sale but the inventory has been increasing. The number of homes on the market is now at 5.1 months and is gradually rising. Realtors believe that a 5.0 month supply is required to balance the demand for and supply of homes. Homeowners who have been reluctant to sell are beginning to put their houses back on the market. If the inventory level climbs above the desired 5.0 month supply it should give some leverage to home buyers and cause home prices to fall.
 .
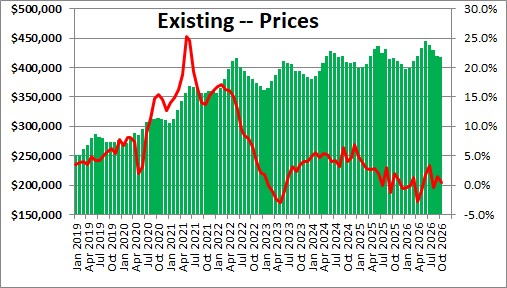
Home prices declined 0.4% in October to $416,700 after falling 2.2% in September.. The year-over-year change is now 0.4%. Look for a slight decline in home prices in 2027.
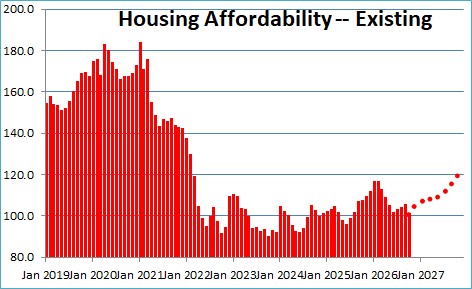
Housing affordability is dependent on three factors — home prices, mortgage rates, and consumer income. Jobs growth is climbing slowly which boosts consumer income, Mortgage rates may decline somewhat in 2027. And home prices should also decline. As a result, housing affordability should climb in the months ahead and the median-income earning family will have about 20% more income than required to purchase a median-priced home by the end of 2027.
.
Given all of the above we expect existing home sales to rise 12.5% in 2027 and reach 4,300 thousand by the end of that year.
We expect to see 2.8% GDP growth in the fourth quarter which would give us 2.7% GDP growth for this year as a whole, and we expect 2.6% GDP growth next year.
Stephen Slifer
NumberNomics
Charleston, S.C.
Follow Me