
November 2, 2026
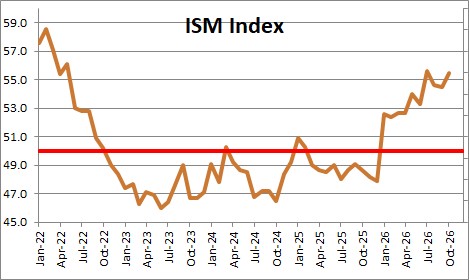
The Institute for Supply Management’s index of conditions in the manufacturing sector rose 1.0 point in October to 55.5 after having fallen 0.1 point in September. This is the 10th straight month that the manufacturing sector has been expanding following a 10-moonth period of contraction. It also is essentially at its highest level since May 2022, A level of 54.5 is associated with a GDP increase of 2.7%.
The ISM organization does a similar survey for the services sector. The ISM index of conditions in the service sector for October will be released on Wednesday, November 4.
The Institute for Supply Management Chair for the Survey Committee Susan Spence said, “In October, U.S. manufacturing activity remained in expansion territory. Of the five subindexes that make up the PMI®, four (New Orders, Production, Supplier Deliveries and Inventories) grew faster than the previous month, while Employment growth slowed down by 0.3 percentage point. In October, general sentiment got worse for a third month in a row, with 34 percent of the comments positive and 66 percent negative (a 1-to-2 ratio of positive to negative sentiment). Among negative comments, pricing volatility was mentioned in 62 percent, longer lead times 41 percent, tariffs 25 percent and the Iran war 21 percent; most comments mentioned multiple factors.
“In October, three of four demand indicators (the New Orders, Backlog of Orders and New Export Orders indexes) remained in expansion, and the Customers’ Inventories Index remained in ‘too low’ territory, contracting at the same rate as last month. A ‘too low’ status for the Customers’ Inventories Index is usually considered positive for future production.
“Regarding output, the Production Index expanded for the 12th month in a row, with the positive-to-negative comment ratio improving to 2 positive comments for every negative one (compared to the 1.6-to-1 ratio in September). The Employment Index remained in expansion but lost 0.3 percentage point. The positive-to-negative comments ratio on Employment was 1.8-to-1 in October.
“Finally, inputs (defined as supplier deliveries, inventories, prices and imports) were mixed, with the Supplier Deliveries Index increasing 0.1 percentage point, the Inventories Index gaining 2.8 percentage points and returning to expansion, and the Prices Index decreasing 2.7 percentage points. The Imports Index gained 1.9 percentage points, to 52.9 percent versus 51 percent in September.”
Comments from respondents include the following:
- “Negative, inflation, in the red’ are the three words or phrases that best describe our strategic sourcing for 2026. We generally assume inflation at 2 percent to 3 percent year over year, and we usually do a great job keeping costs under the 2-percent increase. This year, costs are up more than 6 percent, and we are not doing much to keep any of the spend categories under the target. Of the tracked items, only nine are lower, 24 are higher and six are neutral. The red is a bit disturbing. Despite the cost pressures, sales have been OK. It won’t be a great year. It’s hard to get excited about OK or just getting by. U.S. economic policy has suffered another year, making it impossible to make sound long-term decisions.” [Chemical Products]
- “Global demand for capital scientific instrumentation assets has slowed due to continued uncertainty in the Middle East, Eastern Europe and China. Anticipation over the midterm elections and impact to funding for scientific research and the National Institutes of Health also is impacting customers’ purchasing behavior, making them focus on optimizing existing technology and tools.” [Computer & Electronic Products]
- “Economic policies coming out of Washington continue to weigh on business conditions. Customers are unwilling to make commitments to anything other than the shortest term due to the vast uncertainty. Canadian tariffs continue to damage small U.S. businesses selling into that important market.” [Fabricated Metal Products]
- “Inflationary pressures and volatile commodity markets continue to create challenging scenarios and unfavorable impact to purchase price variance. Diesel rates and the trucker shortage are impacting costs beyond the raw material inputs to levels I have never seen.” [Food, Beverage & Tobacco Products]
- “Business remains strong, largely driven not only by data centers and mission critical infrastructure, but also the continued replacement of municipal infrastructures particularly related to water. Mining continues to be strong as well.” [Machinery]
- “Explosive growth in the semiconductor and government/defense spaces has put us on our heels as we try to work through demand. The long-awaited wave has arrived for our company, and it seems the global supply chain is in similar straits. Lead times and prices are increasing, and some carry COVID-19 era delays — four weeks is now 50 weeks; a US$2,000 item six months ago is now $4,000. We are hand-to-mouth. All the while, our customers are breaking down the doors complaining about our delivery delays.” [Machinery]
- “New month, same trends: Any commodity consumed by AI/data centers is in a crunch, both for supply and pricing. We keep wondering when the madness will stop. In spite of these challenges, our demand remains strong and the supply chain is getting by, albeit with a lot of work. As we plan next year’s budget, it’s sobering to roll up the annualized impact of (1) remaining tariffs, (2) AI-impacted commodity price increases and (3) price increases related to geopolitically influenced commodities.” [Miscellaneous Manufacturing]
- “Customers continue to be in a wait-and-see mode. There is no momentum to purchase, as our customers’ customers aren’t in urgent need of equipment. There has been tentative talk of 2027 purchases, but no discussion of larger-than-historical needs moving into the new year. Customers continue to be gobsmacked by the high price of equipment when they ask for quotes. Typically, we see a fourth-quarter bump as customers use up end-of-year budgets. This year, that bump does not exist.” [Transportation Equipment]
- “The trucking industry is experiencing mixed signals. While major companies are making significant strategic investments and consolidations (acquisitions, autonomous technology and electric vehicle infrastructure), underlying freight demand appears softer. Truck tonnage metrics are declining year-over-year, new-vehicle sales are falling, and consumer confidence is weakening. However, elevated diesel prices continue to support trucking company revenues through fuel surcharges, even as freight volumes remain challenged. The economy is growing at a moderate pace, with inflation concerns persisting.” [Transportation Equipment]
- “Material shortages abound. Fuel remains high. Uncertainty remains constant. Though not a presidential election, the election-year dynamic has begun to take hold a bit. Canadian tariffs continue to have a negative impact on steel.” [Primary Metals]
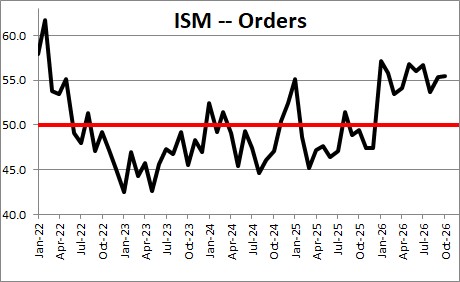
The orders component rose 0.2 point in October to 55.5 after having risen 1.6 points in September. “Of the six largest manufacturing industries, four (Machinery; Computer & Electronic Products; Transportation Equipment; and Chemical Products) reported increased new orders. Demand sentiment in October was 1.8 positive comments for every negative comment, a very slight improvement from last month’s 1.7-to-1 ratio,” says Spence.
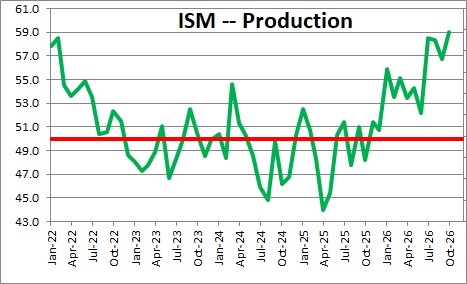
The production component rose 2.3 points in October to 59.0 after having declined 1.6 points in September. . This is the index’s highest reading since it registered 60.5 percent in November 2021. “Of the six largest manufacturing industries, four (Computer & Electronic Products; Transportation Equipment; Machinery; and Chemical Products) reported increased production. Panelists had a 2-to-1 ratio of positive to negative comments regarding output, up from September’s 1.6-to-1 ratio,” says Spence.
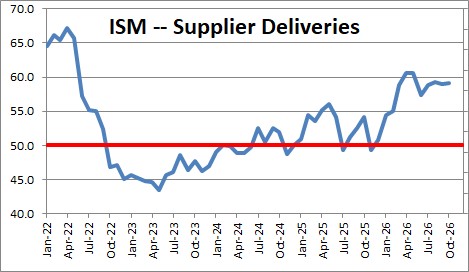
The delivery performance of suppliers to manufacturing organizations rose 0.1 in October to 59.1 after having fallen 0.3 point in September. This is the eleventh consecutive month this index has been above 50.0. A reading above 50 indicates slower deliveries which presumably means that the economy in beginning to accelerate. A reading below 50 indicates faster deliveries and is associated with slower growth in the economy. It had been hovering between 50-53 for the past year but it has broken out to the upside. “The Supplier Deliveries Index registered 59.1 percent, 0.1 percentage point higher than September’s reading of 59 percent. Of the six big industries, five (Computer & Electronic Products; Machinery; Transportation Equipment; Chemical Products; and Food, Beverage & Tobacco Products) reported slower supplier deliveries,” says Spence
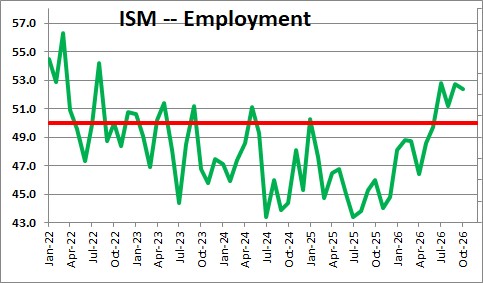
The employment index fell 0.3 point in October to 52.4 after having risen 1.5 points in September. “Of the six big manufacturing industries, four (Machinery; Transportation Equipment; Computer & Electronic Products; and Food, Beverage & Tobacco Products) reported higher levels of employment in October. The panelist comment ratio of hiring to managing/reducing head counts was 1.8-to-1,” says Spence.
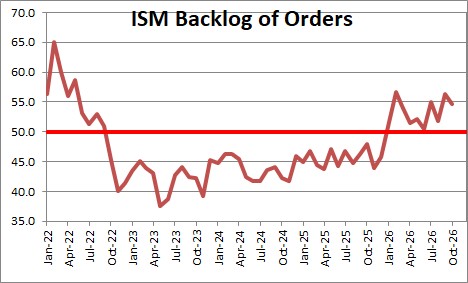
The backlog of orders declined 1.8 points in October to 54.6 after having jumped 4.6 points in September. Eleven industries reporting higher backlogs in October Three industries reported lower inventories. Four industries reported no change in backlog of orders in October This is a positive sign for factory output in the months ahead.
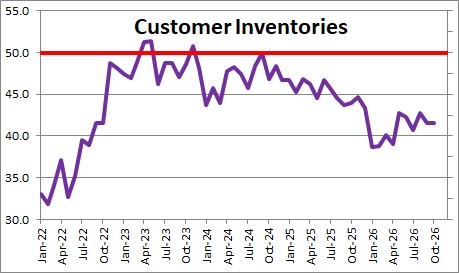
Customer inventory levels were unchanged in October at 41.6 after having fallen 1.2 points in September. Customers’ Inventories Index remained in “too low” territory.
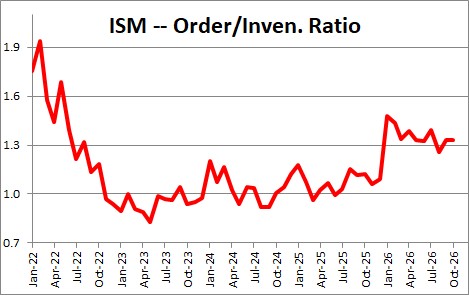
With a small increase in orders and no change in customer inventories the ratio of orders to inventories was unchanged in October at 1.3. The 1.3 level for this index suggests that production should climb further in the months ahead.
The prices paid component fell 2.7 point in October to 75.2 after having jumped 6.8 points in September. “The Prices Index reading is still being driven by (1) increases in steel and aluminum prices that impact the entire value chain, (2) tariffs applied to many imported goods and (3) increases in petroleum-based products as a result of the Middle East conflict. Higher prices were reported by 53.1 percent of respondents in October, down 5.5 percentage points from September’s 58.6 percent,” says Spence.
GDP rose 3.4% in the third quarter and is expected to climb 2.8% in the fourth quarter. We are also looking for GDP growth of 2.7% in 2026 followed by 2.4% growth in 2027.
Stephen Slifer
NumberNomics
Charleston, S.C.
Follow Me